Sacha Ryszfeld

AI and quantitative finance

Sacha Ryszfeld

Engineering student at Télécom Paris, on a gap year as a research intern in AI and systematic investing at Université Paris Dauphine-PSL.

Looking for a six-month off-cycle internship in trading or quantitative finance, starting February 2027.

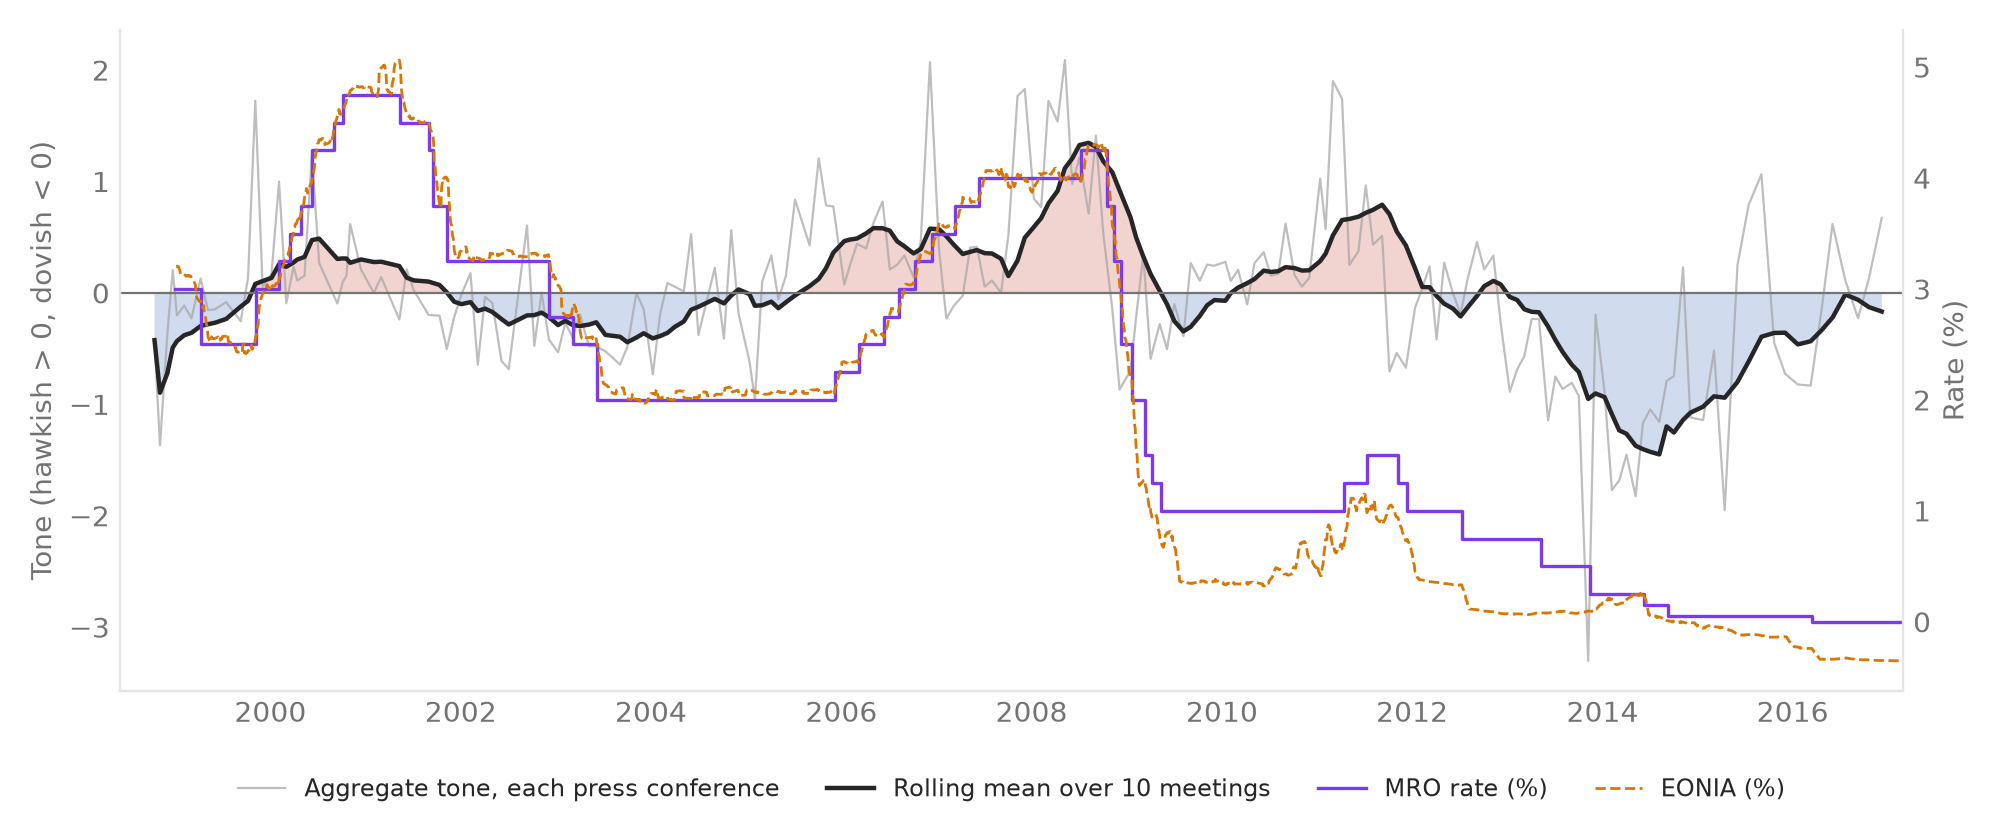
The tone of 205 ECB press conferences, 1998 to 2016: hawkish above the line, dovish below, averaged over 10 meetings. From my replication of Czudaj and Nguyen (2025).

About

I am an engineering student at Télécom Paris, where I studied probability, statistics, optimization and machine learning, from linear models to deep generative models. Before that, I prepared the engineering school entrance exams in preparatory classes (PSI*) at Lycée Claude Bernard.

I am spending my gap year at Université Paris Dauphine-PSL, as a research intern in AI and systematic investing with Prof. Serge Darolles. I work on a trading strategy for European equities that reads financial news with large language models, and on the execution side that makes it run every day: order sizing, rebalancing and monitoring.

I am also starting to contribute to Prof. Darolles’ research on dynamic portfolio allocation, with score-driven models that update the portfolio weights directly instead of first estimating expected returns and covariances, and their extension to large portfolios.

Alongside the internship, I follow the Empirical Finance course of Dauphine’s Master 222 (portfolios and factor models), and I study derivatives and fixed income on my own.

Outside of work, I enjoy playing the guitar, swimming, and automating bits of my daily life with AI.

Projects

  • Decision under uncertainty
  • Dynamic programming
  • Monte Carlo

A search agent for Flip 7

An agent for the two-player card game Flip 7, where each turn you either draw another card or bank your points. It combines an expectiminimax search over the current round with a table of game-winning probabilities learned by approximate policy iteration.

55.8%of 2,000 games won against a greedy expected-score strategy

  • Graph neural networks
  • Time series
  • LightGBM

Relational learning on H&M sales

Do graph neural networks on a relational database beat a flat table with LightGBM? On H&M weekly article sales, a controlled ablation shows that the signal is autoregressive, not relational, and that the best graph model uses no message passing at all.

0 hopsis the best graph model, and LightGBM beats every graph configuration

  • Computer vision
  • Deep learning
  • Imbalanced data

White blood cell classification

Classifying microscope images of white blood cells into 13 very imbalanced classes, from a baseline on handcrafted features to a fine-tuned ConvNeXt-Tiny with XGBoost on its embeddings, validated by 5-fold stratified cross-validation.

0.726macro-F1 of the fine-tuned ConvNeXt-Tiny in 5-fold cross-validation

  • Optimization
  • Inverse problems
  • PyTorch

Image restoration, Tikhonov vs Total Variation

Denoising and deblurring formulated as optimization problems, solved in closed form in the Fourier domain and by gradient descent in PyTorch, comparing a quadratic smoothness prior with Total Variation.

+1.5 dBof PSNR for Total Variation over Tikhonov in deblurring, and SSIM 0.67 against 0.58

Experience and education

  1. Aug 2026 to present

    Experience

    Research intern, AI and systematic investing

    Université Paris Dauphine-PSL, DRM Finance

    Research internship supervised by Prof. Serge Darolles, on trading strategies that use large language models to read financial news.

    • Developed an event-driven paper-trading strategy on European equities, with signals generated from financial news by local LLMs running on GPUs.
    • Automated the daily rebalancing: VWAP-based order sizing, cash and position checks, and protection against duplicate orders.
    • Built a Euronext VWAP pipeline for order sizing, with 94.9% price coverage across 649 stocks in a live validation.
    • Built a dashboard tracking six portfolios against the STOXX Europe 600: performance, exposures, cash and orders.
    • Contributing to ongoing research on score-driven portfolio allocation and its high-dimensional extensions.
  2. Sep 2025 to present

    Experience

    Oral examiner in engineering sciences

    Lycée Claude Bernard, Paris

    Weekly oral examinations of preparatory class students: assessing their technical reasoning and giving immediate feedback.

  3. 2024 to 2028

    Education

    Engineering degree (Master’s level), computer vision, AI and data science

    Télécom Paris, Institut Polytechnique de Paris

    First year of the master’s cycle completed, gap year in 2026-2027. Coursework in probability, statistics, linear models, optimization for machine learning, deep learning, generative models (GANs, VAEs, diffusion) and computer vision.

  4. 2021 to 2024

    Education

    Preparatory classes, PSI*

    Lycée Claude Bernard, Paris

    Intensive mathematics and physics for the competitive entrance exams to French engineering schools. Ranked in the top 10% of the Mines-Ponts exam (365th of 3,664).

Get in touch

I am looking for an off-cycle internship in trading or quantitative finance from February 2027. The fastest way to reach me is by email.

Email me